Insurance carriers advertise bundled home and auto insurance policies as an effortless way to save hundreds of dollars off your annual premiums. While multi-policy discounts are real and sometimes an excellent value, they are only one part of the big picture.
When exploring bundled insurance options, or any insurance options for that matter, it’s essential to compare pricing for the actual coverage you will get. Bundled home and auto insurance policies that produce significant savings for the coverage they offer may be a great fit for your needs, but they are not always the easy answer to saving money.
What Does it Mean to Bundle Home and Auto Insurance?
Bundling simply means buying more than one insurance policy from the same provider. As a reward for giving a single company your business for multiple lines of insurance, the carrier usually applies a multi-policy discount to your annual premiums.
Bundled home and auto policies are never merged into a single policy. Home insurance and auto insurance are two separate products with completely separate contracts. Each policy has its own liability limits, coverage terms, and deductibles. Bundled policies are also not restricted to homeowners insurance. Renters and condo owners are eligible to bundle their policies with auto insurance. Additionally, motorcycle insurance or an umbrella policy can be bundled with home insurance.
Because every insurance contract is distinct in a multi-policy scenario, a claim on one does not have an impact on any others. For example, a car accident will not raise your homeowners insurance rate. Keep in mind that due to your personal circumstances, you may qualify for better or worse coverage on either type of insurance, even from the same carrier. This is why it is so important to work with a knowledgeable agent who looks beyond the advertised discounts associated with bundling.
How Much Can You Save by Bundling Home and Car Insurance?
Every major insurance provider that offers multiple lines of coverage issues discounts for bundling policies. The discounts vary by carrier, and they may even vary by the type of coverage being purchased.
Depending on the carrier, your state, your credit history, and your specific risks, you can qualify for discounts between 5% and 25% across all of your annual premiums. Most carriers advertise discounts as being “up to” a certain percentage. The actual savings vary by type of policy. For example, one carrier may offer a 5% discount on homeowners insurance and a 15% discount on auto premiums while another offers a flat 10% discount across all policies. Once you know what the discount is for each policy, compare the final price to a non-discounted rate for the same coverage with another carrier.
Which Companies Offer Discounts for Bundling Homeowners with Auto Insurance?
Since all leading carriers provide discounts for bundled policies, the real question is which company’s rates work best for your specific home and vehicles. Independent insurance agencies that work with multiple carriers have access to rate and policy comparisons across regional and national providers. They are able to perform a comprehensive search based on their client’s actual needs in order to find the best balance of coverage and pricing.
Some of the top-rated carriers that offer competitive multi-policy discounts for clients who bundle home and auto coverage include:
-
Liberty Mutual: Known for customizable policies, flexible homeowner policy endorsements, and attractive bundling discounts
-
Progressive: Often recognized for competitive auto rates and strong discounts when bundled with homeowners, condo, and renters insurance
-
Travelers: Frequently provides robust multi-product discounts and is known for excellent rates on high-value homes and older vehicles
Your insurance agent can also pull rates from their full network of carriers to ensure that you are able to review the full scope of pricing and coverage across all brands.
Is Bundling Home and Auto Worth It?
It is always worthwhile to review the discounts you may get by bundling multiple policies under the same insurance provider. Those discounts can amount to hundreds of dollars in savings on your annual premiums. Additionally, it is very convenient to access all of your policies through one login account and pay one bill when premiums are due. Bundled plans also run on the same renewal cycle, making it easier to cover all of your updates in one conversation.
Even with the discounts and convenient management, bundled insurance plans are not automatically the most practical option. The discount on a high-priced policy might not bring the premium down to a lower rate than another provider. Two individually priced policies at separate carriers often cost less in overall premiums. It really depends on how various insurance companies price different policy details. For example:
-
One carrier might offer excellent rates for your zip code, but their inflated homeowners premiums due to the age of your roof wipe out the benefit of the discount.
-
A particular carrier could offer the best coverage and endorsements that work for Bucks County owners of stone farmhouses, but their rates for teen drivers are sky high.
-
If a claim on your auto policy erases the discount during renewal, but your homeowners rate stays competitive, splitting the policies could be most affordable.
Below is a simple table showing how to compare bundled and individual carrier rates:
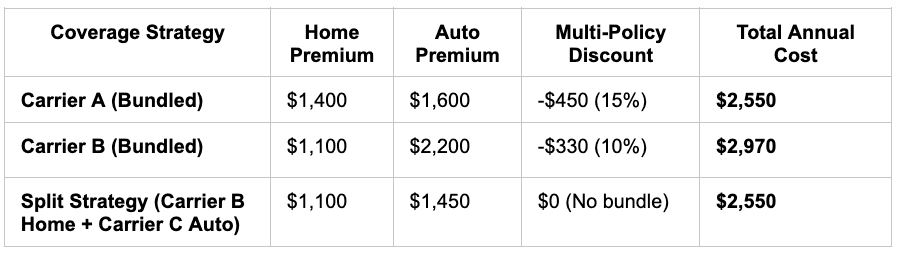
In the above example, the bundled option with a multi-policy discount comes in at the same annual cost as splitting premiums between two carriers. The next step is to look at the entire scope of coverage to make sure that the policies are actually comparable in detail:
-
Liability Limits: Do bodily injury, property damage, and personal liability coverage match your real asset exposure?
-
Physical Damage Limits: Are the comprehensive and collision deductibles for auto plus property wind/hail and water damage deductibles in line with what you can afford?
-
Essential Endorsements: Do all of the policies have extra protections that fit your specific needs for both home and auto?
-
Policy Exclusions: Will either policy restrict your coverage to something less robust than you currently have?
Whether or not bundling makes the most financial sense right now, it is always a good idea to keep an eye on your options. Your annual policy renewal is the perfect time for a conversation to look at rates and available discounts. But anytime you have a significant change to your household or driving needs, it is worth reviewing with your local insurance agent. Changing the number of drivers in your house, making significant property changes, or buying a new home or car will change the way your insurance works and what it costs.
An Independent Insurance Agency Compares Bundled Rates for the Best Value
Bundling is a smart tool for simplifying your insurance accounts and taking advantage of discounts. At the same time, bundling should not be a foregone conclusion based on the savings alone. The right choice always comes down to assessing the total value of your policies. The goal is to maximize your protection while keeping your combined out-of-pocket costs as low as possible.
 At Freedom Insurance Group, we have proudly served homeowners and drivers with comprehensive solutions throughout Bucks County, Montgomery County, Northeast Philadelphia, and New Jersey for over 20 years. Because we are an independent insurance agency, we are not bound to a single carrier when exploring the best products for your needs. Our team evaluates your current policies, shops your coverage across more than 20 leading providers, and compares bundled packages against standalone options to find the right fit for your budget.
To find out if bundling your home, renters, condo, and auto policies under one company will save you the most money, complete our quick online quote request or call our team at 215-673-0300. We will schedule a personalized insurance review to help you find the best policy and rates.
Frequently Asked Questions
Is it always cheaper to bundle home and auto insurance?
Not always. Carriers offer discounts for bundling home and auto policies, but separate policies from different companies can sometimes cost less overall.
Does bundling insurance affect my coverage?
No. Multi-policy discounts are applied to the annual premiums after you select the coverage you want for each policy. This means that the final price you pay still depends on your total coverage.
Can I bundle insurance if I already have policies with different companies?
Yes. You can move one or both policies to the same carrier where you already have an existing policy in order to take advantage of bundling discounts.
Should I choose the company with the biggest bundling discount?
Not necessarily. Always work with your agent to compare the final premium and coverage rather than the advertised discount alone.